

The global banking elite left Davos yesterday battered and bruised by the latest round of the blame game over the world financial crisis.
Scolded by presidents, prime ministers, central bank chiefs and even billionaire investors over regulation and their salaries, the heads of the institutions that dominate the financial markets have had to admit that some kind of reform is necessary.
US President Barack Obama’s plans to limit the size and activities of banks prompted an urgent call at the World Economic Forum for new regulations coordinated on an international level.
PHOTO: EPA
Bankers at first acted with shock. But they were jolted by criticism of their attitude.
“Don’t feel sorry for yourselves,” British Chancellor of the Exchequer Alistair Darling said.
And now ministers and bankers agree that if there are rules they have to be for every country.
“We must have global rules to treat global issues. This is absolutely essential. If not, it’s a recipe for catastrophe,” said Jean-Claude Trichet, head of the European Central Bank, at the Davos forum in Switzerland.
IMF managing director Dominique Strauss-Kahn said “my fear is that we may forget key lessons of crisis that is coordination.”
He was “a bit afraid that we’re not exactly going in that direction.”
During the London G20 summit on the crisis last April, world leaders asked the Financial Stability Board and the Basel Committee to draft new banking regulations.
The issue was left to the two institutions while governments turned their focus to lifting economic crisis management.
In September, the issue was brought up at the Pittsburgh summit. Britain and France made a call in December for a global banking regulation pact, and have since both followed that up by announcing a tax on traders’ bonuses.
Obama announced plans to limit banks’ size and activities, forcing them to choose between proprietary activities such as trading in stocks and sometimes risky financial instruments for their own benefit — and traditional activities, like making loans and collecting deposits.
The initiative annoyed some politicians in Europe who said that it went against the international coordination principles agreed on by the G20.
“Giving in to unilateralism, to ‘every man for himself,’ would also be an economic, political and moral error,” French President Nicolas Sarkozy said in his keynote address to the forum, even though he agreed with the essence of Obama’s plans.
In an interview, German Economy Minister Rainer Bruederle said: “Due to competition between financial centers, we should not implement [reforms] in an isolated way on a national or European basis.”
The private sector has also asked for international coordination. Tidjane Thiam, who heads British insurance group Prudential, said “consistency” was needed.
Josef Ackermann, chairman of Deutsche Bank, said an international harmonization of regulations was required.
Standard Chartered bank’s group chief executive Peter Sands asked for Asia’s voice to be taken into account on reforms.
“What we don’t want is a situation where we shape the future regulatory reform too dominated by Western voices with the effect of Asia having to take medicine for an illness” that it didn’t have, he said, pointing out that the region’s banks suffered little from the crisis.
In a sign of the urgency of the issue, ministers, bankers and central bankers held an informal meeting at Davos on Saturday.
Representative Barney Frank, chairman of the US House of Representatives’ Financial Services Committee, who took part in the meeting, said bankers now saw there would have to be “tough” regulation.
“There’s going to be regulation, they understand that. We are willing to talk to people about the specifics of how to achieve the goals, but ... there is general agreement that there has to be international coordination,” Frank said. “They aren’t in charge of this. The political leadership certainly in the US is going to go ahead with tough, sensible regulation.”
STOCK, CASH: Quarterly profit-sharing bonuses would supplement payments under the Incentive Pay Plan, offering ‘transparency’ and ‘predictability,’ an executive said Micron Memory Taiwan Co (台灣美光) yesterday unveiled a new profit-sharing program and structural wage hikes as part of its efforts to build a predictable and transparent compensation framework in response to feedback from unions. The memorychip maker, a subsidiary of US-based Micron Technology Inc, announced the major compensation structural overhaul during an online news conference following a milestone agreement with the union representing more than 10,000 workers at its Taichung facility. Under the new framework, quarterly profit-sharing bonuses would supplement payments under the Incentive Pay Plan (IPP), the company said. The IPP formula has also been substantially enhanced, it said. “Profit-sharing mechanisms are common
Micron Memory Taiwan and a union representing workers at its Taichung operations today said they had signed a labor-management agreement covering multiple issues, prompting both sides to withdraw from mediation scheduled for tomorrow. The joint statement did not disclose the terms of the agreement, saying the company and the union would separately communicate details to affected employees in the coming days. Idaho-based Micron, the world's third-largest memory chipmaker, employs about 15,000 people in Taiwan, a key manufacturing base where it produces DRAM and high-bandwidth memory chips used in artificial intelligence (AI) servers. Any disruption to Micron's Taiwan operations could affect already strained global
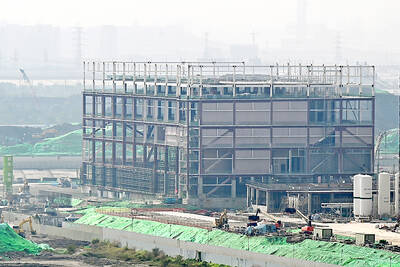
Taiwan Semiconductor Manufacturing Co (TSMC, 台積電) is suspending some construction work after an accident at one of its building sites in southern Taiwan led to the deaths of four workers. The incident took place on Tuesday during steel structure construction at TSMC’s Fab 22 in Kaohsiung, the company said. Workers fell from a height while performing steel structure hoisting and installation, a report from the Central News Agency said. A cause might be aged bolts, it said, citing a preliminary assessment by the Southern Taiwan Science Park Bureau. The bureau said that work would only resume after Shang Hao Machinery Co (上昊機械),
China proposed adding advanced artificial intelligence (AI) technologies to its export-control list, potentially restricting overseas transfers of AI models and chip designs in an effort to keep closer control over homegrown advancements in a strategically important sector. The draft proposal covers 23 AI technologies, including large language models, agents, chip designs and computing clusters. Restricted technologies would include model weights and source code for products exceeding certain performance thresholds. Chinese AI startups have this summer made significant progress in closing the gap on US industry leaders. Models such as Moonshot (月之暗面) AI’s Kimi K3 and DeepSeek’s (深度求索) latest editions offer better pricing,


 RSS