

The key to economic development and ending poverty is investment. Nations achieve prosperity by investing in four priorities. Most important is investing in people, through quality education and healthcare. The next is infrastructure, such as electricity, safe water, digital networks and public transport. The third is natural capital, protecting nature. The fourth is business investment. The key is finance: mobilizing the funds to invest at the scale and speed required.
In principle, the world should operate as an interconnected system. Rich countries, with high levels of education, healthcare, infrastructure and business capital, should supply finance to poorer countries, which must urgently build up human, infrastructure, natural and business capital.
Money should flow from rich to poor countries. As emerging-market countries become richer, profits and interest would flow back to rich countries as returns on their investments.
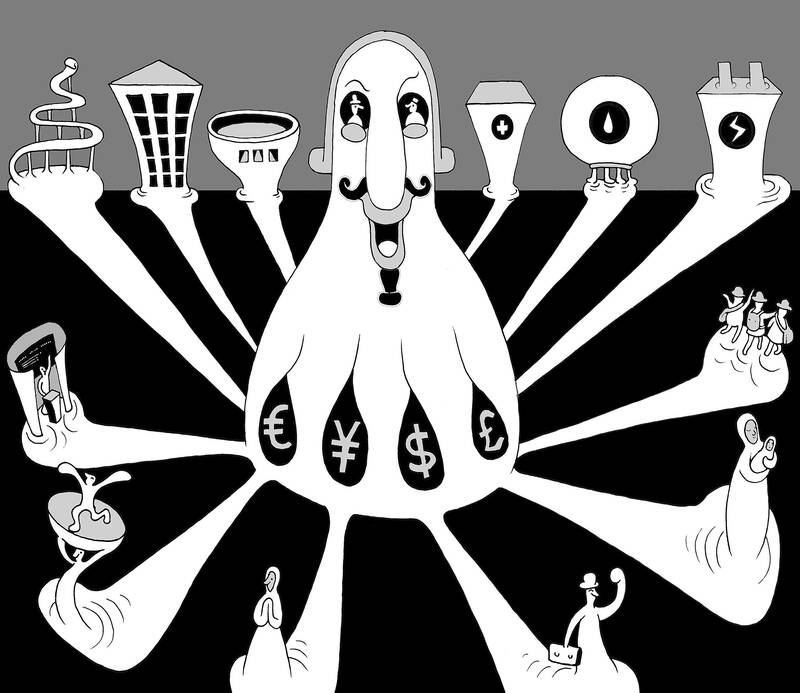
Illustration: Mountain People
That is a win-win proposition. Rich and poor countries would benefit. Poor countries become richer, and rich countries earn higher returns than if they invested only in their own economies.
Strangely, international finance does not work that way. Rich countries invest mainly in rich economies. Poorer countries get only a trickle of funds, not enough to lift them out of poverty. The poorest half of the world — low-income and lower-middle-income countries — produces about US$10 trillion per year, while the richest half of the world — high-income and upper-middle-income countries — produces about US$90 trillion.
Financing from the richer half to the poorer half should be about US$2 trillion to US$3 trillion per year. In reality, it is a small fraction of that.
The problem is that investing in poorer countries seems too risky. This is true in the short run. Suppose that the government of a low-income country wants to borrow to fund public education. The economic returns to education are very high, but need 20 to 30 years to realize, as today’s children progress through 12 to 16 years of schooling and only then enter the labor market.
However, loans are often for only five years, and are denominated in US dollars rather than the national currency.
Suppose the country borrows US$2 billion today, due in five years. That would be fine if in five years, the government can refinance the US$2 billion with another five-year loan.
With five refinance loans, each for five years, debt repayments are delayed for 30 years, by which time the economy would have grown sufficiently to repay the debt without another loan.
However, at some point along the way, the country would likely find it difficult to refinance the debt. Perhaps a pandemic, a Wall Street banking crisis or election uncertainty would scare investors.
When the country tries to refinance the US$2 billion, it finds itself shut out from the financial market. Without enough money to hand, and no new loan, it defaults, and lands in the IMF emergency room.
Like most emergency rooms, what ensues is not pleasant to behold. The government slashes public spending, incurs social unrest and faces prolonged negotiations with foreign creditors. In short, the country is plunged into a deep financial, economic and social crisis.
Knowing this in advance, credit-rating agencies such as Moody’s Investors Service and S&P Global give the countries a low credit score, below “investment grade.”
As a result, poorer countries are unable to borrow long term. Governments need to invest for the long term, but short-term loans push governments to short-term thinking and investing.
Poor countries pay very high interest rates. While the US government pays less than 4 percent per year on 30-year borrowing, the government of a poor country often pays more than 10 percent on five-year loans.
The IMF advises the governments of poorer countries not to borrow very much. In effect, the IMF tells the government that it is better to forgo education — or electricity, safe water or paved roads — to avoid a debt crisis. That is tragic advice. It results in a poverty trap, rather than an escape from poverty.
The situation has become intolerable. The poorer half of the world is being told by the richer half: decarbonize your energy system; guarantee universal healthcare, education and access to digital services; protect your rainforests; ensure safe water and sanitation; and more.
However, they are somehow to do all of this with a trickle of five-year loans at 10 percent interest.
The problem is not with the global goals. These are within reach, but only if the investment flows are high enough. The problem is the lack of global solidarity. Poorer nations need 30-year loans at 4 percent, not five-year loans at more than 10 percent. They need much more financing.
Poorer countries are demanding an end to global financial apartheid.
There are two ways to accomplish this. The first is to expand about fivefold the financing by the World Bank and the regional development banks — such as the African Development Bank. Those banks can borrow at 30 years and about 4 percent, and on-lend to poorer countries on those favorable terms. Yet their operations are too small. For the banks to scale up, G20 countries — including the US, China and EU nations — need to put a lot more capital into those multilateral banks.
The second way is to fix the credit-rating system, the IMF’s debt advice and the financial management systems of the borrowing countries. The system needs to be reoriented toward long-term sustainable development.
If poorer countries can borrow for 30 years, rather than five years, they would not face financial crises in the meantime. With the right kind of long-term borrowing strategy, backed by more accurate credit ratings and better IMF advice, poorer countries would access much higher flows on much more favorable terms.
The major countries have four meetings on global finance this year: in Paris in June, Delhi in September, the UN in September and Dubai in November.
If big countries work together, they can solve this. That is their real job, rather than fighting endless, destructive and disastrous wars.
Jeffrey D. Sachs, a professor and director of the Center for Sustainable Development at Columbia University, is president of the UN Sustainable Development Solutions Network. The views expressed in this column are his own.
Taiwan’s domestic political situation is following recognizable political rhythms, while the international environment surrounding Taiwan is undergoing a major transformation. Within Taiwan, there are ongoing battles between the legislative and executive branches over the budget, and between cities and the central government over resources. Tensions between political parties dominate headlines and consume much of the attention of party leaders. Jockeying is underway for local elections this November and national elections in 2028. And the longstanding philosophical debate inside Taiwan over how best to protect Taiwan and promote the good life remains unresolved. Amidst all of this, Taiwan continues to function well. It
With candidate registration for this year’s local elections closed on Sept. 4 and the elections less than 80 days away, Democratic Progressive Party (DPP) Legislator and Taipei mayoral candidate Puma Shen’s (沈伯洋) rapidly growing popularity has become the focus of political talk shows and online discussions over the past week, heating up the mayoral election race in Taipei. Local media headlines and political pundits have picked up his supporters’ slogan “ocean current” (洋流) — a play on the last character of Shen’s name, which literally means “ocean” (洋), and the character (流), which can mean “current,” “flow” or “trend” — to
At the 18th BRICS Summit in New Delhi, people will remember less what China achieved and more what the global south attained. China did not lose face: President Xi Jinping (習近平) was an honored guest in India, was endorsed as the chair of BRICS for next year, and China is to host the next summit. Yet the carefully crafted 140-paragraph New Delhi Declaration (NDD), the longest BRICS declaration so far, reveals a subtle, but important shift. BRICS is moving from a loose grouping toward a more substantive platform for the global south, giving developing countries greater voice and bargaining space
As of the end of last month, Taiwan had a total population of 23,224,721, declining for the 32nd consecutive month, the latest household registration data released on Thursday by the Ministry of the Interior showed. The figure was down 103,622 from a year earlier — or an average decline of 283.9 per day — and 10,281 from the previous month. Last month, Taiwan recorded 7,492 births — averaging about one baby every 6 minutes — dropping by 972 from the same month last year and 414 from July. From January to last month, the number of newborns was 61,742, decreasing by


 RSS